KEY HEADLINES & INSIGHTS
Cocoa Capital launches GH¢16.3bn financing programme: Cocoa Capital PLC is raising up to GH¢16.3 billion through domestic debt markets, with GH¢14 billion earmarked for cocoa purchases and GH¢2.3 billion for refinancing existing COCOBOD debt.
Bank of Ghana to launch new Heritage Series cedi notes: The upgraded notes will be introduced on November 3, 2026, with enhanced security and durability, while existing cedi notes will remain legal tender and circulate alongside them.
Ghana has increased the cocoa producer price to GH¢42,400 per tonne for the 2026/27 season, raising the price of a 64kg bag from GH¢2,587 to GH¢2,650. The increase gives farmers a higher share of cocoa export earnings while supporting efforts to improve productivity, traceability and sustainability in the sector.
Higher oil prices are pushing global bond yields higher as markets price in stronger inflation risks and the possibility of tighter interest rates, potentially raising borrowing costs across major economies.
UK stocks rise as homebuilders rally: The FTSE 100 opened 0.26% higher, led by gains in homebuilders as expectations of a revived Help to Buy scheme boosted the sector, while rising oil prices supported energy stocks.
PRIMARY DEBT MARKET ISSUANCE WEEK
Yields on Government of Ghana Treasury bills declined across all three tenors this week, although investor demand softened relative to the previous auction. Total bids for the 91-day, 182-day and 364-day bills amounted to GH¢3.66 billion, down from GH¢3.96 billion at the previous auction but above the government's GH¢2.75 billion target. The 91-day bill yield edged down to 4.6785%, while the 182-day bill fell to 6.3701% and the 364-day bill declined to 9.8339%. Overall, yields continued to ease across the Treasury bill curve, although the latest auction points to more moderate investor demand compared with the previous week.
| Security | Current Wk % | Previous Wk % | Bps |
|---|---|---|---|
| 91-Day GoG Bill | 4.6785 | 4.6941 | -1.56 |
| 182-Day GoG Bill | 6.3701 | 6.4895 | -11.94 |
| 364-Day GoG Bill | 9.8339 | 9.9820 | -14.81 |
Source(s): Bank of Ghana
GHANA FIXED INCOME MARKET VOLUME TRADED
The Ghana Fixed Income Market (GFIM) recorded approximately GH₵6.94 billion in traded volume across 2,844 transactions during the week. Treasury Bills accounted for the largest share of turnover at 69.54%, while also dominating transaction activity with 91.60% of all trades, reflecting their continued importance as highly liquid short-term government securities. DDEP Bonds accounted for 22.38% of total traded volume across 2.92% of transactions, indicating that activity in these securities was concentrated in relatively larger-value trades. Sell/Buy Back Trades involving GoG Notes & Bonds contributed 7.64% of total turnover across 3.62% of transactions, consistent with their role in short-term liquidity and funding management. Corporate Bonds accounted for 0.36% of traded volume and 1.27% of transactions, while New GoG Notes & Bonds contributed 0.08% of turnover across 0.42% of transactions. Old GoG Notes & Bonds remained marginal, accounting for 0.01% of total traded volume and 0.18% of transactions. Overall, the week’s GFIM activity was heavily concentrated in Treasury Bills, which accounted for more than two-thirds of total traded volume and over nine-tenths of all transactions. DDEP Bonds remained the second largest contributor to turnover, generating a substantial share of traded volume through comparatively fewer transactions, while activity in the remaining security categories was relatively limited.
Daily Volume (GHS) Traded – GFIM
Week's Yield Curve
EQUITY MARKET
Trading activity on the Ghana Stock Exchange recorded 25.53 million shares traded at a total value of approximately GH₵145.82 million during the week.The Telecommunications sector led market activity with 21.72 million shares valued at GH₵136.58 million, making it the largest contributor to both traded volume and value and accounting for approximately 93.66% of total traded value. The Financial sector followed with 2.17 million shares worth GH₵4.12 million, while Food & Beverage recorded 102,410 shares valued at GH₵1.46 million. Insurance recorded 138,898 shares worth GH₵790,749, while mining recorded 9,246 shares valued at GH₵494,830.
Oil & Gas recorded 49,202 shares valued at GH₵366,467, followed by healthcare with 324,848 shares worth GH₵225,985. Technology recorded 34,236 shares valued at GH₵141,460, while Agriculture accounted for 70,574 shares valued at GH₵111,644. Advertising recorded 181,893 shares valued at GH₵74,041. Trading activity in Manufacturing remained limited at 9,251 shares valued at GH₵2,405, while Education recorded only 57 shares valued at GH₵6.84. Overall, trading activity was heavily concentrated in the Telecommunications sector, which accounted for approximately 85.08% of total shares traded and 93.66% of total market value traded during the week.
| Index | Level | WoW% | MoM% | YoY% |
|---|---|---|---|---|
| GSE-CI | 13,886.7400 | -2.954 | -7.890 | 58.339 |
| FSI | 7,562.4400 | 0.946 | -4.328 | 62.732 |
| Market Cap (Bn) | 266.2718 | -1.454 | -6.760 | 54.771 |
Source(s): Ghana Stock Exchange
Week's Equities Top Gainers & Laggards
EQUITY MARKET MOST TRADED STOCKS
| Ticker | Traded Volume | Price (GHS) |
|---|---|---|
| MTNGH | 21,716,041.00 | 6.22 |
| CAL | 1,841,688.00 | 0.73 |
| KASA | 698,014.00 | 1.79 |
| IIL | 238,560.00 | 0.51 |
| ETI | 232,077.00 | 1.69 |
Source(s): Ghana Stock Exchange
TOP PERFORMING AFRICAN STOCK INDICES YEAR-TO-DATE
| Country | Index | Level | YTD % |
|---|---|---|---|
| Tanzania | DSE-ASI | 4,682.13 | +69.52 |
| Zimbabwe | ZSE-ASI | 465.90 | +67.67 |
| Nigeria | NGX-ASI | 252,113.41 | +62.01 |
| Ghana | GSEC-CI | 13,886.74 | +58.34 |
| West Africa (BRVM) | BRVM-CI | 540.78 | +56.41 |
Source(s): African Markets
COMMODITY MARKET
Commodity markets recorded mixed performance during the week. Brent crude rose 0.43% to US$104.32 per barrel, supported by continued Middle East supply risks, with elevated oil prices also affecting fuel costs across Africa.
Gold declined 2.34% to US$4,321.20 per ounce, reflecting a stronger U.S. dollar and expectations of tighter monetary policy. Gold remains important to Ghana's export earnings and foreign-exchange inflows, supporting the country's external position.
Cocoa rose 5.48% to US$5,619 per tonne, although it remained lower monthly and year-on-year. The rebound was supported by renewed concerns over dry weather and crop conditions in West Africa, particularly Côte d'Ivoire and Ghana, ahead of the new cocoa season.
Overall, oil remained supported by geopolitical risks, gold faced monetary-policy pressures, while cocoa benefited from renewed West African supply concerns.
Source(s): Yahoo Finance, Trading Economics
CURRENCY MARKET
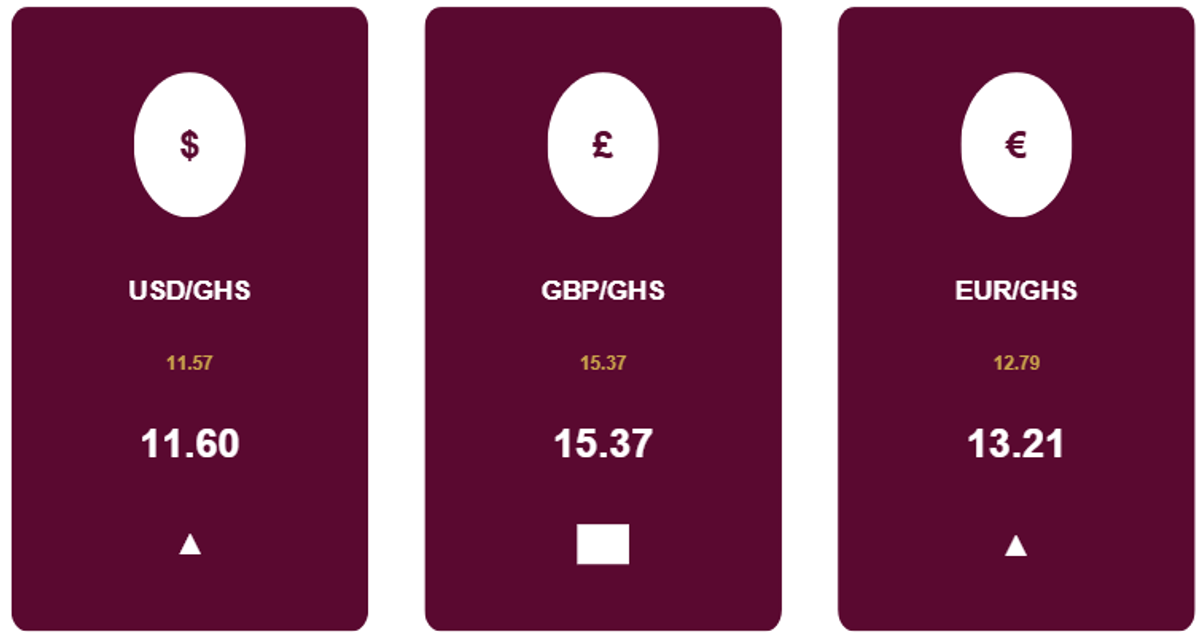
The Ghanaian cedi recorded mixed movements against the major trading currencies during the week. The USD/GHS rate stood at GH¢11.60, with the cedi unchanged on a weekly basis, while depreciating by 3.20% monthly, 2.84% quarterly and 6.42% year-on-year against the US dollar.
The EUR/GHS rate stood at GH¢13.21, reflecting a 3.28% weekly depreciation of the cedi against the euro. The cedi also weakened by 1.33% monthly, 2.56% quarterly and 7.16% year-on-year against the euro.
The GBP/GHS rate stood at GH¢15.37, with no recorded movement across the weekly, monthly, quarterly or yearly periods.
Overall, the cedi recorded no weekly movement against the US dollar and pound, while weakening against the euro. Over the longer periods, the cedi recorded depreciation against both the US dollar and euro, with the euro recording the largest year-on-year depreciation at 7.16%.
Source(s): Bank of Ghana